COT DASHBOARD · NQ · ES
NQ & ES COT report: Nasdaq-100 and S&P 500 futures positioningNQ dealers net short 94,122 contracts
Weekly CFTC Commitments of Traders (COT) data for E-mini Nasdaq-100 (NQ) and E-mini S&P 500 (ES) futures, plus the micro contracts MNQ and MES: net positions of leveraged funds, asset managers and dealers from the Traders in Financial Futures report, with 1-year and 3-year percentiles. Positions as of 20 Oct 2026, released 23 Oct 2026. NQ dealers' net position is at the 4th percentile of the last 156 weekly reports, the furthest from the middle of its 3-year range among the NQ and ES groups.
This week as a permanent page: COT report 20 Oct 2026 · All weekly reports
E-mini Nasdaq-100 NQ
CFTC code 209742 · NASDAQ 100 STOCK INDEX X $20 · net position = long minus short, contracts
| Group | Long | Short | Net | Week change | 1y pct | 1y min / max | 3y pct | 3y min / max |
|---|---|---|---|---|---|---|---|---|
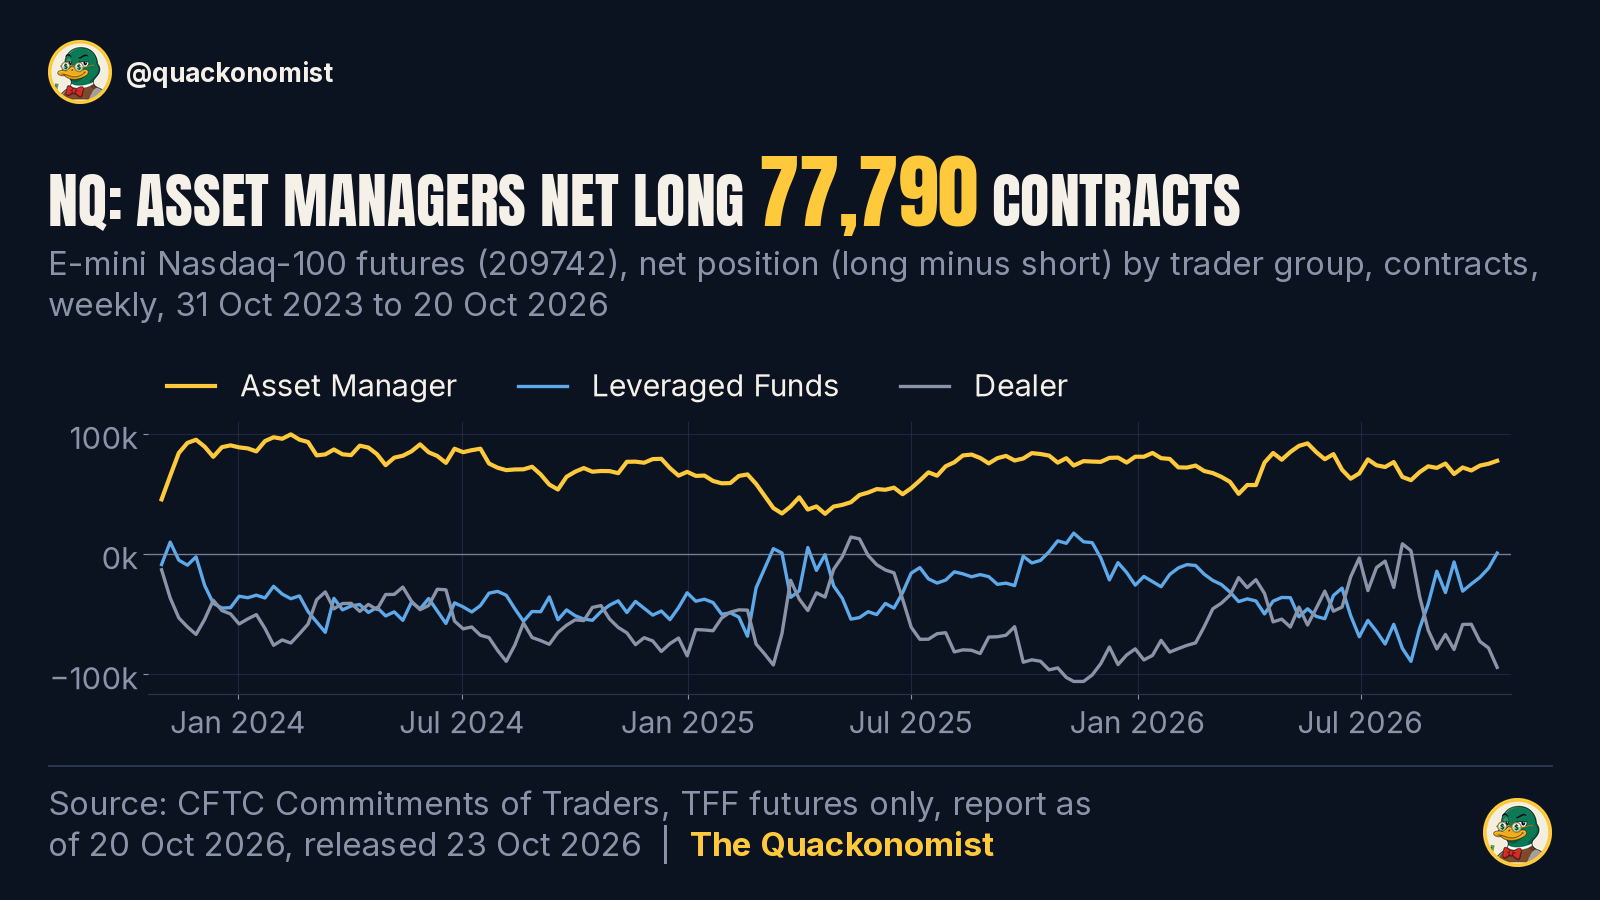
| Asset Manager | 109,985 | 32,195 | 77,790 | +2,467 | 67th | 50,270 / 92,301 | 60th | 33,676 / 99,783 |
| Leveraged Funds | 51,749 | 50,799 | 950 | +12,543 | 90th | −89,125 / 17,619 | 94th | −89,125 / 17,619 |
| Dealer | 38,475 | 132,597 | −94,122 | −16,190 | 12th | −105,846 / 8,749 | 4th | −105,846 / 14,344 |
What the data shows
- Asset managers were net long 77,790 contracts, the highest net position since the 7 Jul 2026 report, 15 weeks earlier; that is the 60th percentile of the last 156 weekly reports.
- Leveraged funds were net long 950 contracts, the highest net position since the 25 Nov 2025 report, 47 weeks earlier; that is the 94th percentile of the last 156 weekly reports. The previous week they were net short 11,593.
- Dealers were net short 94,122 contracts, the lowest net position since the 25 Nov 2025 report, 47 weeks earlier; that is the 4th percentile of the last 156 weekly reports.
- The largest week-over-week change of the three groups was in dealers: their net position fell by 16,190 contracts.
E-mini S&P 500 ES
CFTC code 13874A · $50 X S&P 500 INDEX · net position = long minus short, contracts
| Group | Long | Short | Net | Week change | 1y pct | 1y min / max | 3y pct | 3y min / max |
|---|---|---|---|---|---|---|---|---|
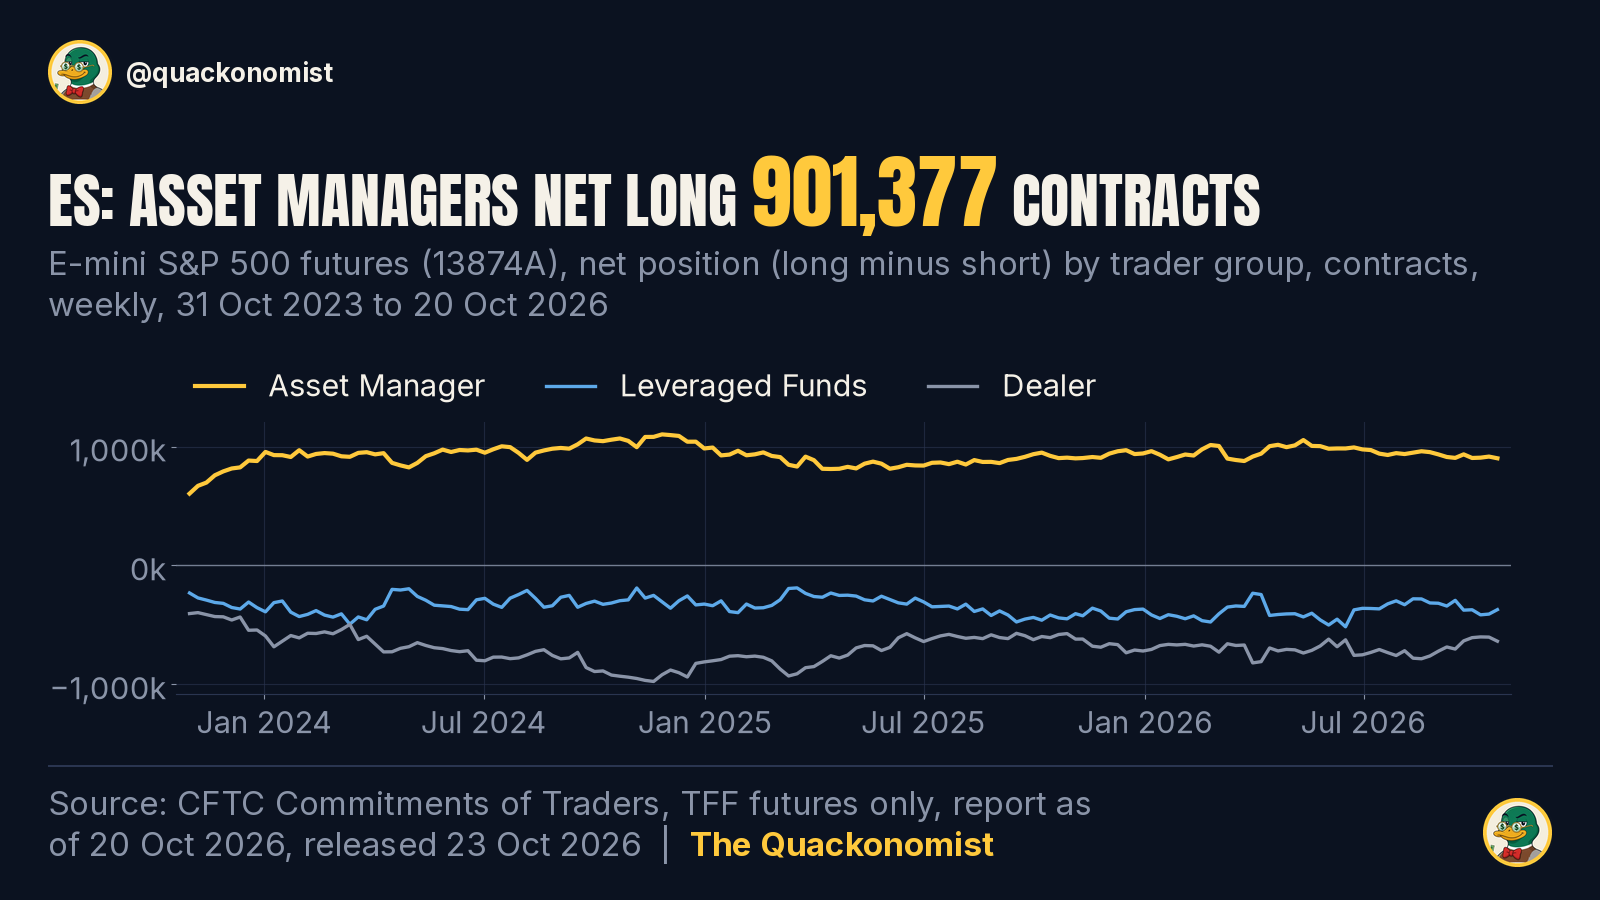
| Asset Manager | 1,101,642 | 200,265 | 901,377 | −14,458 | 12th | 878,391 / 1,054,872 | 30th | 604,196 / 1,102,458 |
| Leveraged Funds | 135,034 | 506,279 | −371,245 | +37,481 | 62nd | −515,520 / −233,412 | 36th | −515,520 / −188,500 |
| Dealer | 184,740 | 821,671 | −636,931 | −34,573 | 83rd | −819,324 / −572,880 | 69th | −975,338 / −396,534 |
What the data shows
- Asset managers were net long 901,377 contracts, the lowest net position since the 24 Mar 2026 report, 30 weeks earlier; that is the 30th percentile of the last 156 weekly reports.
- Leveraged funds were net short 371,245 contracts, the 62nd percentile of the last 52 weekly reports and the 36th percentile of the last 156.
- Dealers were net short 636,931 contracts, the 83rd percentile of the last 52 weekly reports and the 69th percentile of the last 156.
- The largest week-over-week change of the three groups was in leveraged funds: their net position rose by 37,481 contracts.
Micro contracts
Separate CFTC rows. Micro contracts are one tenth of the E-mini size, so contract counts are not directly comparable with NQ and ES.
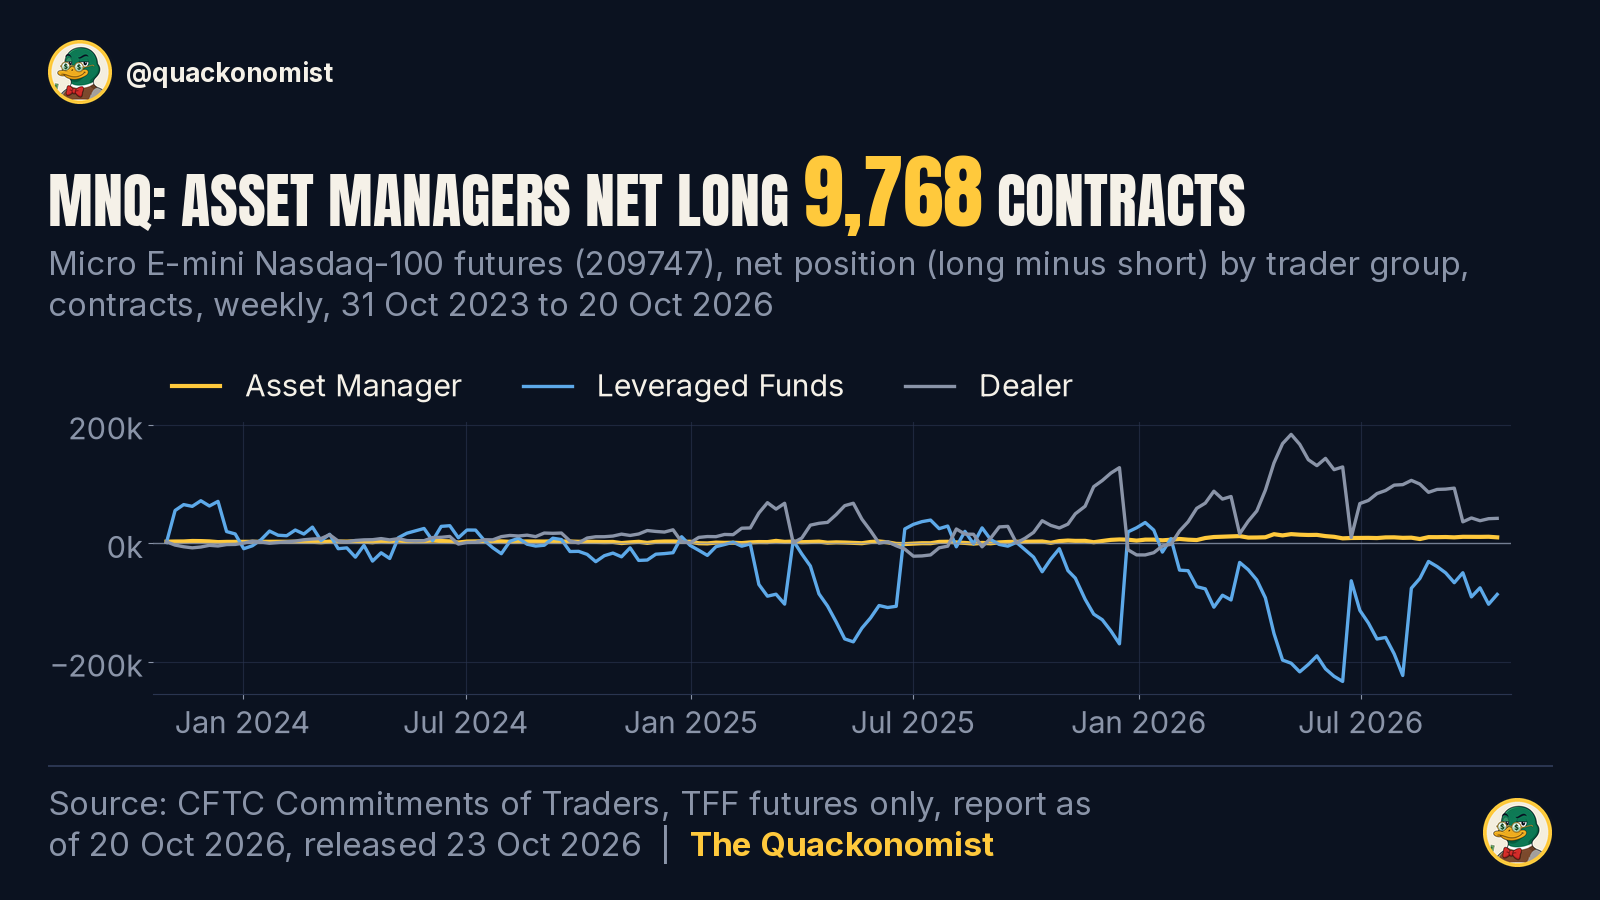
Micro E-mini Nasdaq-100 MNQ
CFTC code 209747 · NASDAQ 100 STOCK INDEX x $2 · net position = long minus short, contracts
| Group | Long | Short | Net | Week change | 1y pct | 1y min / max | 3y pct | 3y min / max |
|---|---|---|---|---|---|---|---|---|
| Asset Manager | 10,247 | 479 | 9,768 | −1,022 | 60th | 1,552 / 15,215 | 87th | −1,543 / 15,215 |
| Leveraged Funds | 8,979 | 95,360 | −86,381 | +16,597 | 52nd | −233,143 / 34,802 | 24th | −233,143 / 71,515 |
| Dealer | 54,296 | 12,488 | 41,808 | +558 | 33rd | −19,853 / 183,379 | 73rd | −21,991 / 183,379 |
What the data shows
- Asset managers were net long 9,768 contracts, the 60th percentile of the last 52 weekly reports and the 87th percentile of the last 156.
- Leveraged funds were net short 86,381 contracts, the 52nd percentile of the last 52 weekly reports and the 24th percentile of the last 156.
- Dealers were net long 41,808 contracts, the 33rd percentile of the last 52 weekly reports and the 73rd percentile of the last 156.
- The largest week-over-week change of the three groups was in leveraged funds: their net position rose by 16,597 contracts.
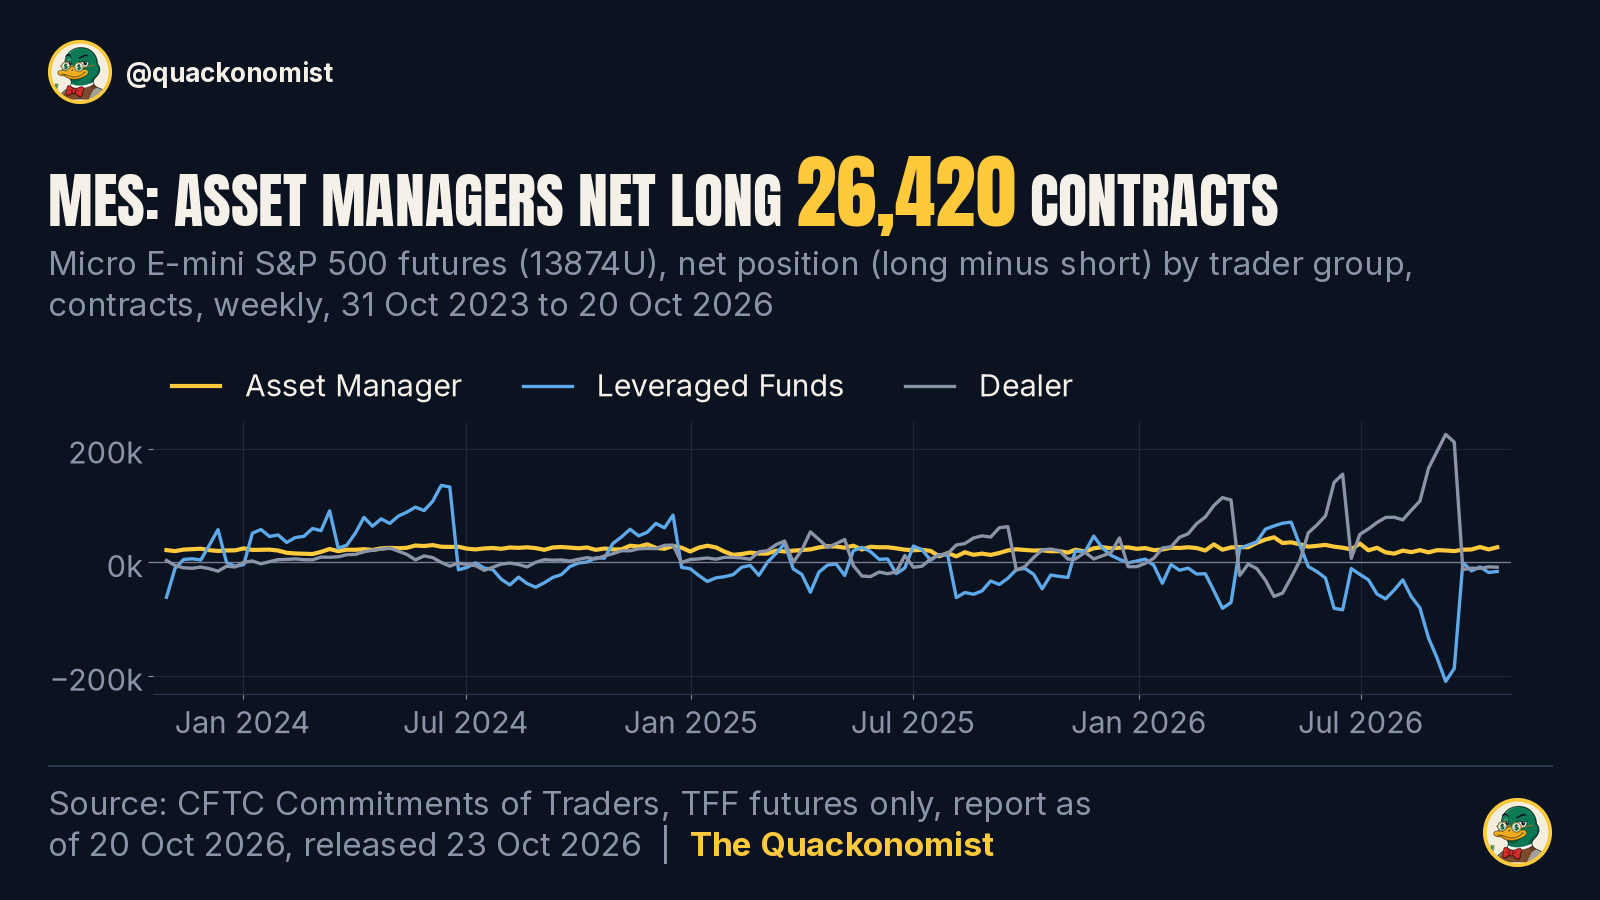
Micro E-mini S&P 500 MES
CFTC code 13874U · $5 X S&P 500 INDEX · net position = long minus short, contracts
| Group | Long | Short | Net | Week change | 1y pct | 1y min / max | 3y pct | 3y min / max |
|---|---|---|---|---|---|---|---|---|
| Asset Manager | 26,616 | 196 | 26,420 | +3,795 | 69th | 15,239 / 44,010 | 79th | 10,401 / 44,010 |
| Leveraged Funds | 76,560 | 92,807 | −16,247 | +1,671 | 50th | −209,829 / 70,696 | 36th | −209,829 / 135,307 |
| Dealer | 6,862 | 15,454 | −8,592 | −529 | 19th | −60,177 / 225,199 | 15th | −60,177 / 225,199 |
What the data shows
- Asset managers were net long 26,420 contracts, the 69th percentile of the last 52 weekly reports and the 79th percentile of the last 156.
- Leveraged funds were net short 16,247 contracts, the 50th percentile of the last 52 weekly reports and the 36th percentile of the last 156.
- Dealers were net short 8,592 contracts, the 19th percentile of the last 52 weekly reports and the 15th percentile of the last 156.
- The largest week-over-week change of the three groups was in asset managers: their net position rose by 3,795 contracts.
About this data and methodology
The Commitments of Traders (COT) report is published every week by the U.S. Commodity Futures Trading Commission (CFTC). This page uses the Traders in Financial Futures (TFF) version, futures only (options are not included). It shows the positions of large traders in E-mini Nasdaq-100 (NQ), E-mini S&P 500 (ES), Micro E-mini Nasdaq-100 (MNQ) and Micro E-mini S&P 500 (MES) futures, split by trader group.
Timing. Positions are recorded at the close of business on Tuesday. The CFTC normally releases them on Friday at 15:30 Eastern Time (usually 21:30 in Central Europe); releases move after U.S. federal holidays. This page is rebuilt after each release and every number is checked field by field against the official CFTC text report before publication.
Trader groups (CFTC classification, see the TFF explanatory notes): Dealer/Intermediary is the sell side, such as large banks and dealers in securities, swaps and other derivatives. Asset Manager/Institutional covers pension funds, endowments, insurance companies, mutual funds and portfolio managers whose clients are mainly institutional. Leveraged Funds are typically hedge funds and money managers, including registered commodity trading advisors (CTAs) and commodity pool operators (CPOs). The CFTC classifies traders, not individual trades.
Limits. Only reportable positions (traders above CFTC reporting levels) are split by group. "Other reportables" and non-reportable positions are not shown. Futures only, no options. Figures are as published by the CFTC; they describe past positions and are not a forecast.
Archive. Each weekly report has a permanent page with that week's numbers, the changes versus the previous report and the chart: weekly COT report archive.
Calculations
- Net position = long minus short contracts for each group (spreading positions excluded).
- Week change = net position minus the net position in the previous weekly report.
- Percentile = share of weekly net positions in the window that are less than or equal to the latest one. 1y = last 52 weekly reports, 3y = last 156, both including the latest. Range = lowest and highest net position in the same window.
- Groups follow the CFTC Traders in Financial Futures classification: Dealer/Intermediary, Asset Manager/Institutional, Leveraged Funds. Other reportables and non-reportable positions are not shown.
- Data: CFTC Socrata dataset gpe5-46if, filtered by CFTC contract market code. Each build is checked field by field against the official CFTC text report (financial_lf.htm). Machine-readable data: data.json.
COT report FAQ: NQ and ES positioning
What is the COT report for NQ and ES?
The Commitments of Traders (COT) report is a weekly CFTC publication of open positions in U.S. futures markets. Its Traders in Financial Futures (TFF) version splits positions in financial futures such as the E-mini Nasdaq-100 (NQ) and E-mini S&P 500 (ES) into dealers, asset managers, leveraged funds and other reportable traders. This page shows the futures-only figures for NQ, ES, MNQ and MES.
When is the COT report released?
Positions are recorded at the close of business on Tuesday and the CFTC normally publishes them on Friday at 15:30 Eastern Time (usually 21:30 Central European Time). Releases are delayed after U.S. federal holidays. The latest report here shows positions as of 20 Oct 2026, released 23 Oct 2026.
What is the latest Nasdaq-100 futures (NQ) positioning?
In the CFTC report as of 20 Oct 2026, E-mini Nasdaq-100 futures positions were: asset managers net long 77,790 contracts (+2,467 on the week); leveraged funds net long 950 contracts (+12,543 on the week); dealers net short 94,122 contracts (−16,190 on the week).
What is the latest S&P 500 futures (ES) positioning?
In the CFTC report as of 20 Oct 2026, E-mini S&P 500 futures positions were: asset managers net long 901,377 contracts (−14,458 on the week); leveraged funds net short 371,245 contracts (+37,481 on the week); dealers net short 636,931 contracts (−34,573 on the week).
How are leveraged funds positioned in S&P 500 futures in the COT report?
As of 20 Oct 2026, leveraged funds were net short 371,245 E-mini S&P 500 contracts, a week-over-week change of +37,481. That is the 62nd percentile of the last 52 weekly reports and the 36th percentile of the last 156.
What do net position and percentile mean on this page?
Net position is long minus short contracts for a trader group (spreading excluded). The percentile is the share of weekly net positions in the last 52 (1 year) or 156 (3 years) reports that are less than or equal to the latest one. A low percentile means the latest net position is near the bottom of that range, a high percentile near the top.
Why are MNQ and MES shown separately?
The CFTC reports the micro contracts as separate markets. A micro contract is one tenth of the E-mini size, so contract counts are not directly comparable with NQ and ES.
Is this investment advice?
No. The page reports published CFTC data and simple statistics computed from it (net positions, weekly changes, percentiles). It contains no forecasts, price targets or buy or sell recommendations. See the disclaimer below.
Source: CFTC Commitments of Traders, Traders in Financial Futures, futures only, report as of 20 Oct 2026, released 23 Oct 2026
Subscribe to The Quackonomist, free
Disclaimer
Author: The Quackonomist (pseudonym). Publisher: Momentum Finance s. r. o., Ladislava Hudeca 15326/2A, 974 01 Banská Bystrica, Slovakia, IČO 55328067, Commercial Register of the District Court Banská Bystrica, Section Sro, File No. 45986/S; contact: privateequitystock@gmail.com. Data as of: 20 Oct 2026 (positions at close of business, Tuesday); CFTC release 23 Oct 2026, 15:30 ET / 21:30 CEST. Sources: CFTC Commitments of Traders (Traders in Financial Futures, futures only), via publicreporting.cftc.gov; data may be delayed or contain errors.
This page is general market commentary for information and education only. It is not intended as investment advice, an investment recommendation or a suggested investment strategy under Regulation (EU) No 596/2014 (MAR), and it does not consider anyone's personal circumstances. Nothing here is an offer or solicitation to buy or sell any financial instrument or crypto-asset.
Facts are sourced; opinions are clearly labelled. Price levels are reference points (e.g. prior highs/lows, moving averages), not forecasts, targets or signals. Trading futures, FX and crypto-assets carries a high risk of loss; past performance is not a reliable indicator of future results.
Conflicts: The author trades for their own account and may hold long or short positions in instruments discussed, before or after publication. Positions are not disclosed and may change at any time. The Quackonomist receives no payment from any issuer mentioned.